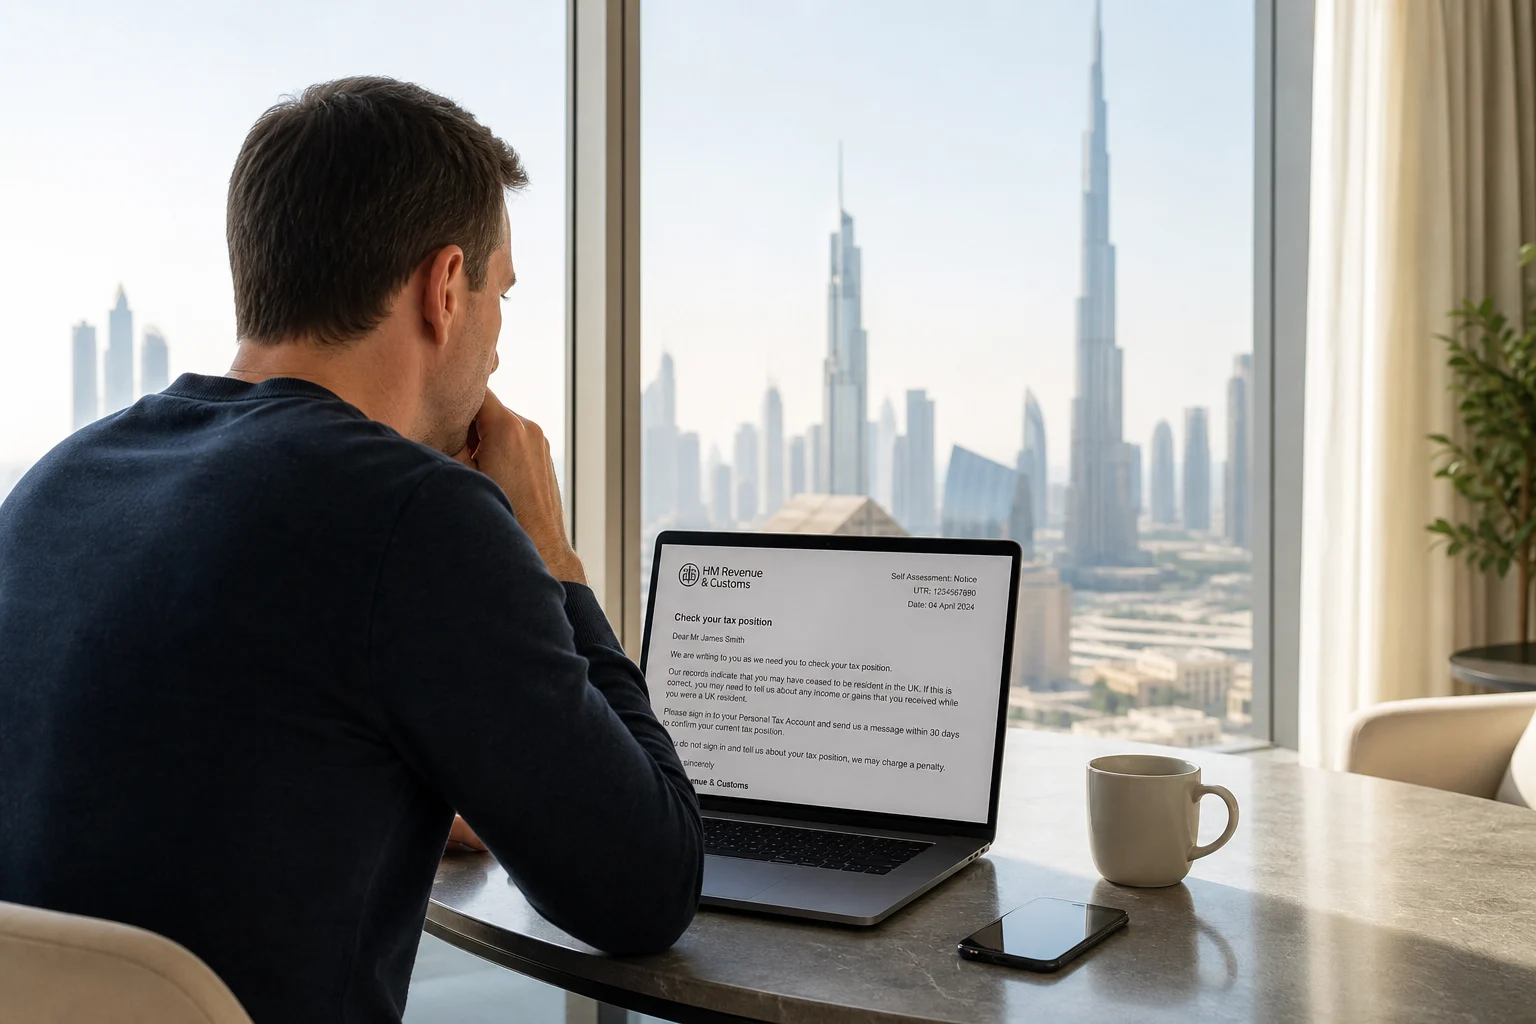
The move to Dubai is easy to plan. The UK departure is not. Most people spend months on the arrival side. They plan the visa, company, apartment, and schools. The departure side gets little attention. That is the mistake that costs money.
HMRC does not care about your Dubai lease. It does not care about your school enrolment either. It cares about UK tax residency. If you do not break that correctly, you can still be a UK taxpayer wherever you live.
The framing problem: people plan the arrival, not the departure
Most people moving to the UAE think about where they are going. They do not think enough about what they are leaving. The UAE side feels exciting. The UK side feels like admin. But the UK side decides whether the tax saving actually happens.
This is not a small issue. It is one of the most common costly mistakes we see from UK professionals moving to the UAE. They get the Dubai side right. They ignore the UK side.
The result often shows up 12 to 18 months later as an HMRC inquiry. By then, the options are narrower and the cost is higher. With three months of pre departure planning, that liability might have been zero. Instead, it can become a six figure bill.
Before you spend too much time on the UAE setup, run a financial break-even analysis. You need to know what the move must deliver. Your UK exit position is part of that number.
What “sorting your UK exit” actually means
Sorting your UK exit means four things. You confirm your position under the Statutory Residence Test. You review any exit tax exposure on assets. You tell HMRC that you have left. You also check any UK income that continues after departure. Each part has its own deadline and its own result if you ignore it.
The statutory residence test
The Statutory Residence Test for UAE movers decides whether HMRC sees you as a UK resident. It is about day counts, home ties, work ties, and family ties. Many people who move to Dubai still pass the SRT. They remain UK resident for part or all of the year. Check your position before you leave.
Exit tax on assets
If you hold shares, funds, or other investments when you leave, UK exit tax on assets may apply. HMRC can treat the move like a sale on departure day. If there is a gain, there is a tax bill. Review this before you go.
Notifying HMRC
The P85 form tells HMRC you have left the UK. It updates your tax code. It can also speed up any refund you are due. It also records your departure date. It is not optional paperwork.
UK income after departure
Many people keep UK income after they move. That can be rent, pension payments, or fees from UK clients. When you actually stop paying UK tax depends on the income type, your residency position, and the treaty. Make the list before you leave.
The most common version of this mistake
The common version looks like this. Someone moves in late winter or spring. They keep a family home in the UK. They also do a few work trips back. By summer, HMRC can treat them as UK resident for the full tax year.
A director earning £180,000 moves to Dubai in March. He has a Dubai apartment and a UAE company. He keeps the family home in the UK because the sale is not simple. His wife and children stay in London until July. He flies back three times for client meetings.
By the time the position is checked, he has a UK home tie, a family tie, and 45 UK days. Under the SRT, he is UK resident for the full tax year. The Dubai move was real. The tax break was not, at least for that year.
His UAE company income for that period may also be taxable in the UK. Add the bonuses in April and the share vesting in May, and the bill is around £80,000. That is the cost of leaving the exit to chance.
Why people leave it too late
The Dubai side feels urgent and visible. You have visa applications, company registration, apartment viewings, and school visits. The UK tax exit feels invisible until HMRC shows up. It does not create its own deadline.
People also want to settle first. They tell themselves they will sort the UK side later. By then, the important choices are already made by default. Default is rarely the right choice.
The time for planning is before you leave. Some steps, especially exit tax and asset disposal, only work before departure. Once you have left, those options are gone.
The six month rule: planning windows that close before you leave
Some of the best UK exit tax steps only work before you leave. You can crystallise losses to offset gains, restructure shareholdings, or time asset sales before departure. After you leave, you cannot go back and do them.
The six months before departure is the live planning window. In that window, you can:
- Review your asset base and note unrealised gains.
- Decide whether to sell before or after departure.
- Restructure company shareholdings if you hold equity.
- Time your final salary payments and bonuses.
- Ensure your P85 is filed correctly and on time.
- Check whether pension lump sums or drawdowns should happen before or after you leave.
None of this is hard if you do it early. Once you leave, much of it is hard to undo.
What “leaving it too late” actually looks like
Leaving it too late means facing HMRC 12 to 24 months after the move. At that point, you respond to HMRC instead of planning ahead. You also explain choices you made without full information. Penalties and interest can cost more than the tax saving.
A typical timeline looks like this.
You move in April. You file the UK self assessment return the next January. HMRC reviews it and sees a non UK residence claim for part of the year. An inquiry lands 6 to 12 months later.
At that point, you need to rebuild your day count. You also need proof of UAE residence. You must show that your UK ties stay within the SRT limits. If you kept a property, had family in the UK, or spent too many days there, you may lose.
If you lose, you pay the tax, plus interest. HMRC may also add penalties. Not knowing the rules does not protect you.
We have written separately about specific UK tax exit mistakes people make during a move. That piece covers the mechanics. This one is about the bigger problem: no planning at all.
What to do instead: the pre departure checklist
Treat the UK exit as the first step of the move. Do not leave it as an afterthought. Start planning 4 to 6 months before departure. By the time you board the flight, your UK tax position should be clear, documented, and filed.
Here is the checklist.
Step 1. SRT assessment
Map out your Statutory Residence Test position before you move. Count your planned UK days for the year of departure. List your ties. Know exactly where you stand. If you are close to a threshold, change the plan.
full Statutory Residence Test breakdown for UAE movers
Step 2. Exit tax review
List every asset you own. That includes shares, funds, investment properties, trusts, options, and carried interest. Ask whether a deemed disposal applies and what the bill looks like. If selling before departure works better, plan the timing.
UK exit tax on assets for UAE movers
Step 3. P85 preparation
Fill in and file the P85 form when you leave. Do not delay it. It tells HMRC you have left, starts any refund process, and fixes your departure date.
Step 4. UK income list
Write down every UK income source that continues after you leave. That includes rent, dividends from a UK company, pension payments, and consultancy income from UK clients. Each one has its own treatment under UK tax law and the treaty.
when you actually stop paying UK tax after moving
Step 5. Ongoing compliance
Moving to the UAE does not end your UK tax obligations. It changes them. You may still need to file a UK self assessment return for several years. You may also need to report UK rental income under the Non Resident Landlord Scheme.
If you want help with compliance from the start, use the tax filing and compliance support. It fits this case.
The UAE move is worth planning well. The UK exit is worth planning first.
Frequently asked questions
What is UK exit planning when moving to the UAE?
UK exit planning means confirming your Statutory Residence Test position and reviewing exit tax on assets. It also means filing the P85 form with HMRC and checking any UK income that continues after you leave. It shows whether your move gives you the tax saving you expect.
Do I need to tell HMRC I am moving to Dubai?
Yes. You notify HMRC using the P85 form. This tells HMRC you have left the UK, triggers a review of your tax position, and may generate a tax refund if you have overpaid during the year of departure.
What happens if I move to Dubai without sorting my UK tax exit?
If you do not plan your UK exit properly, you may still be a UK tax resident. That can happen under the Statutory Residence Test. It can happen even while you live in Dubai. You may keep paying UK income tax on your worldwide income. HMRC often raises inquiries 12 to 24 months later.
Can HMRC still tax me after I move to Dubai?
Yes. UK tax residency does not end automatically when you move. HMRC can assess you as UK resident for the full year if you fail the Statutory Residence Test. UK source income may also stay taxable in the UK under the double tax treaty. That can include rent, dividends, and some pensions.
How many days can I spend in the UK after moving to Dubai?
It depends on your UK ties. Under the Statutory Residence Test, the day limit ranges from 15 to 90 days based on your ties. Those ties can include home, family, and work. You need a personal assessment, not a rule of thumb.
Is UK exit tax planning only for high earners?
Exit tax planning matters most for high earners with large assets. The Statutory Residence Test and P85 duties still apply to everyone who leaves. Even moderate earners who keep UK property or family connections can face unexpected UK tax liabilities.
How far in advance should I plan my UK exit?
Start at least 4 to 6 months before you plan to leave. Some planning steps, especially around asset disposals and shareholding restructures, only work before departure. Leaving it to the month of departure means losing your best options.